How Reorganization Can Reduce or Eliminate SBA Debt
LIMITED AVAILABILITY Consultations are scheduled in the order received. Call today.
SBA Debt Is Different. The Stakes Feel Higher.
- Missed or deferred payments on an EIDL, 7(a), or 504 loan
- Default notices, collection letters, or referral to government collections
- A lien on business assets and an SBA personal guarantee
- Other debt piling on — MCAs, vendors, credit lines — competing for the same cash
The Federal Law That Gives Business Owners Real Leverage With SBA Debt
- Reduce the secured portion of an SBA loan to the value of the collateral, with the rest treated as unsecured debt
- Pay unsecured debt only from what the business can afford over 3 to 5 years
- Stop collection actions and lawsuits once the case is filed
- Deal with MCA and other business debt in the same plan
- Keep you in control of your business
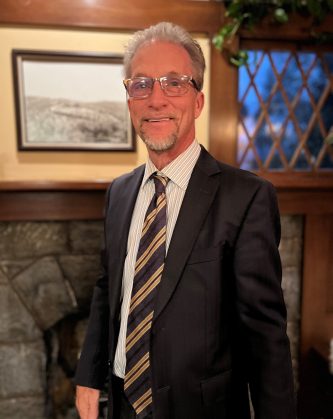
One of the Few True Specialists on SBRA in the Country
— Steven E. Cowen, Esq.
What to Expect
1
Free Consultation
2
Initial Analysis
3
Filing
Trusted by Business Owners Across California
Common Questions About SBA Debt and Reorganization
In many cases it can reduce it substantially. Under a Subchapter V plan, the secured portion of an SBA loan is generally limited to the value of the collateral, and the rest is treated as unsecured debt that is paid only from what the business can afford over three to five years. How much is reduced depends on your collateral, your income, and your other debts, which is why the first step is a review of the actual numbers.
All three are SBA-backed business debt and can be addressed in a reorganization. How each loan is treated depends on its terms and what secures it, so we review your loan documents to see how each one would be handled.
A personal guarantee is a separate obligation, so a reorganization does not erase it automatically. But when the business’s debt is reduced, what a creditor can pursue from you personally may be reduced as well, and in appropriate cases the court can bar creditors from pursuing a guarantor while the plan is carried out. We review each guarantee as part of the analysis.
When your case is filed, an automatic stay generally stops collection actions, including lawsuits, while the court supervises your plan. Government creditors can be subject to special rules in some situations, so we confirm how it applies to your loan.
An SBA settlement (an offer in compromise) is voluntary. The agency can say no or ask for terms the business cannot meet. A Subchapter V plan is a court process, and when the legal requirements are met it can be confirmed even over a creditor’s objection.
Generally, the business must be operating, have debts below the Subchapter V limit, and have enough income to cover its operating expenses and fund a plan. We confirm eligibility during your free consultation.
Don't Wait for Your Lenders to Take Action. Take Action First.
Availability is limited. Call today.
Call (619) 202-7511 or fill out the form below — a member of our team will respond promptly.
Attorney advertising. Every case is different, and prior results do not guarantee a similar outcome. This page is general information and is not legal advice.